Wealth Planning & Retirement: Make the Plan Work for Your Life
Turning savings and investing into a retirement that lasts, by working with a planner who understands your actual life, even if it is multi cultural, multi domicile, multi lingual or multi generational.
Oops! Something went wrong while submitting the form.
International Planning
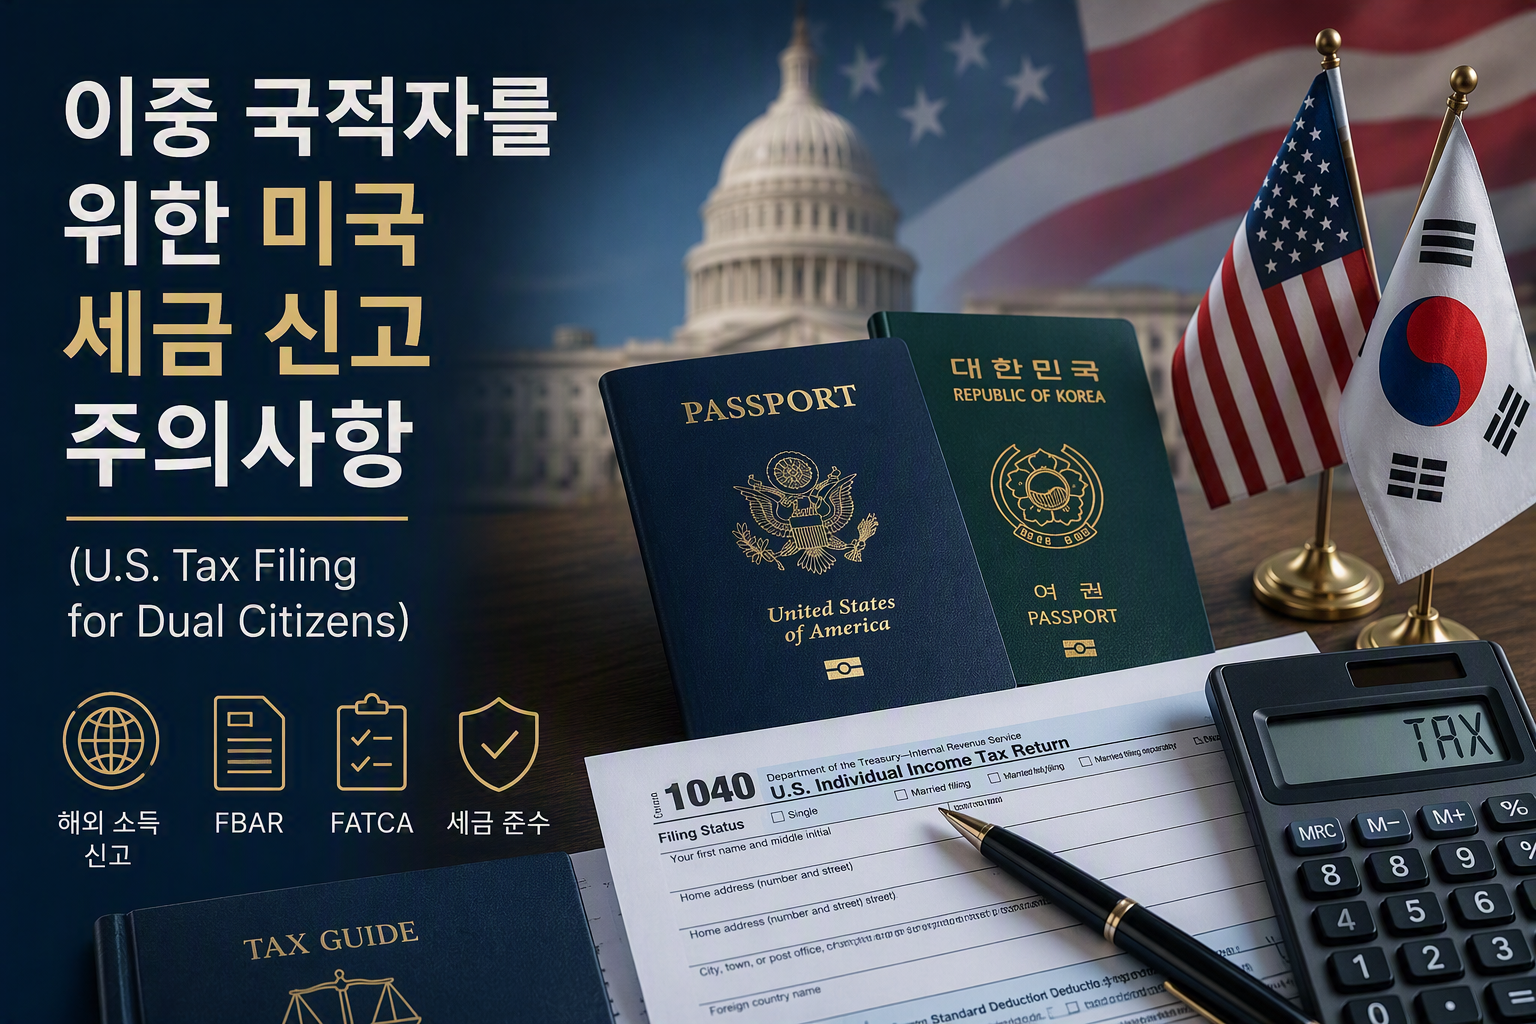
이중 국적자를 위한 미국 세금 신고 주의사항 (U.S. Tax Filing for Dual Citizens)
What if Korea acts on our behalf? We have summarized the essentials regarding FBAR and FATCA review criteria, the parties involved in non-reporting cases, and voluntary disclosure programs.(한국 계좌를 보유한 미국 거주자라면? FBAR·FATCA 신고 기준, 미신고 시 벌금, 그리고 자진 신고 프로그램까지 핵심만 정리했습니다.)
Financial Planning for Korean Americans: What's Different
FBAR and FATCA obligations, family support as a real expense, non-citizen spouses, Korean inheritance, retirement across two countries, and the "Silent Wealth" problem — six ways the standard playbook falls short.
The 401(k) is the workhorse of American retirement — and most people leave money in it unclaimed. Matches, vesting, Roth vs. pre-tax, and menu choices, explained.
The property is simple; the system around it isn't. Ownership rules, two tax codes, currency swings, and inheritance — a pre-purchase checklist for property abroad.
The biggest cross-border dangers aren't high rates — they're unknown obligations. Three deciding questions, five common traps, and a framework for protection.
The company is the family's biggest asset and the least planned. Value drivers buyers actually price, the four exit paths, and the team to assemble early.